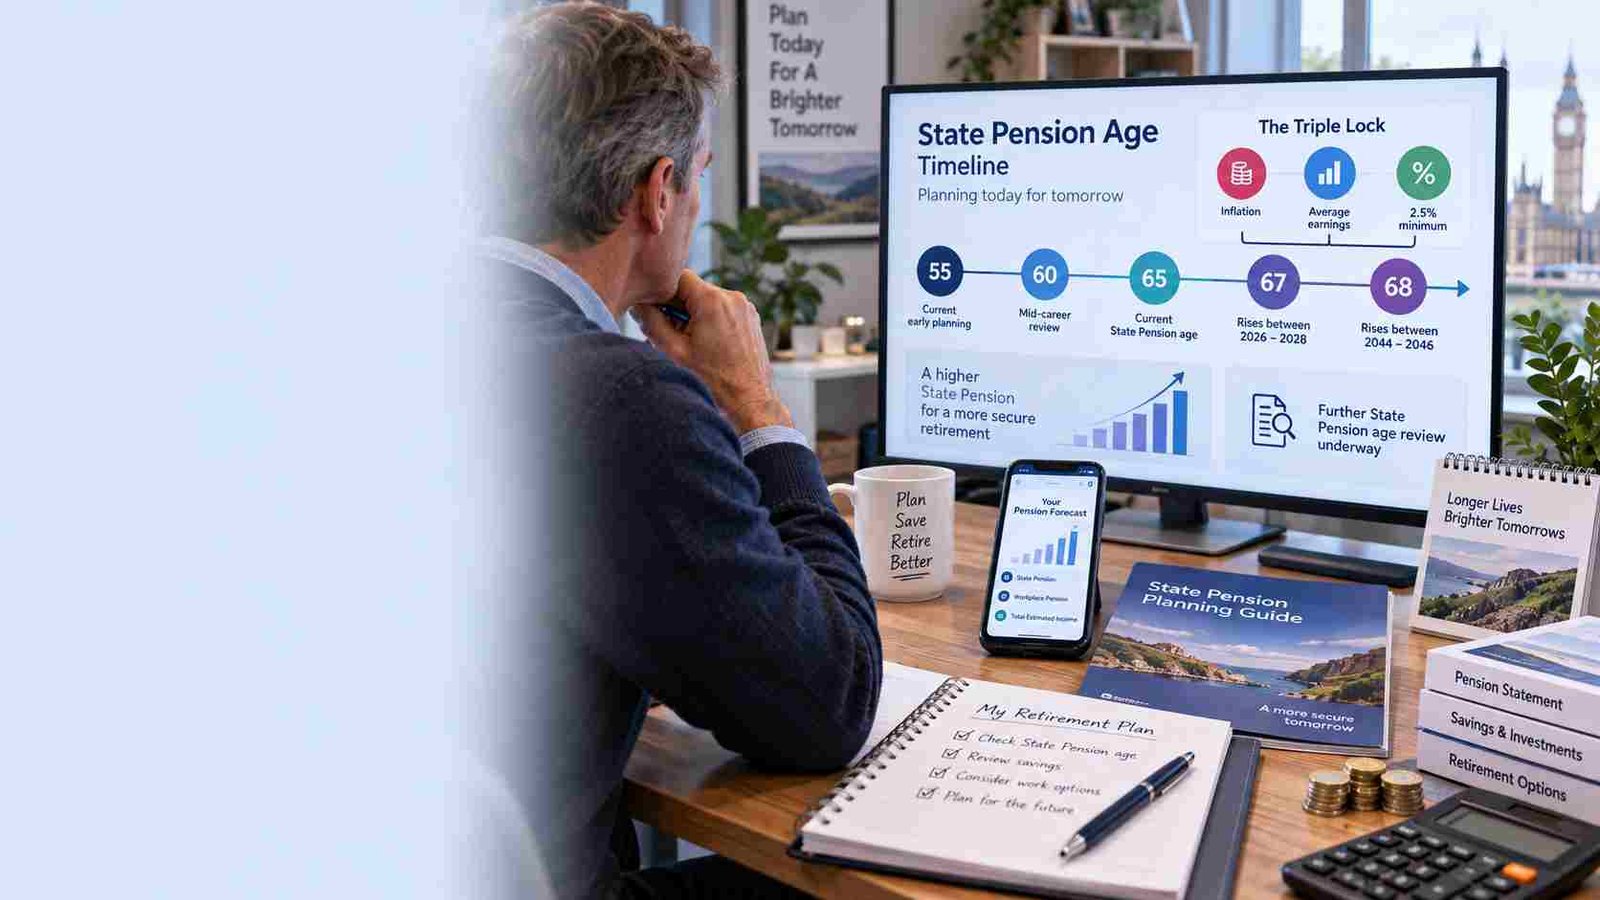
Millions of people aged 55 and under are being encouraged to review their retirement plans after the latest State Pension Triple Lock update reignited debate about the future of the UK’s pension system. While current pensioners continue to benefit from annual increases under the Triple Lock, younger workers are being reminded that the State Pension age could change before they retire.
Experts say future retirees should not assume they will receive their State Pension at the same age as today’s pensioners. Instead, anyone with many years left before retirement may need to prepare for possible changes to both the qualifying age and the amount they eventually receive.
Here’s what the latest update means and why it matters.
What Is the Triple Lock?
The Triple Lock is the policy that determines how the State Pension increases each year.
Under the current system, payments rise by the highest of:
- Average earnings growth
- Inflation
- 2.5%
The policy has helped protect pensioners’ incomes during periods of rising prices, but it has also increased the long-term cost of the State Pension system.
Why Are People Under 55 Being Warned?
The warning is aimed at younger adults because they are more likely to experience future changes before reaching retirement.
Successive governments have already increased the State Pension age in response to longer life expectancy and rising public spending. Further reviews could recommend additional changes over the coming years.
Although no immediate changes have been announced for this age group, retirement experts say planning ahead is becoming increasingly important.
Could the State Pension Age Rise Again?
It is possible.
The Government regularly reviews the State Pension age to ensure the system remains financially sustainable as the population ages.
Any future increase would normally be announced well in advance, giving people time to prepare. However, those currently aged 55 or younger may be more likely to be affected by any long-term reforms.
Will the Triple Lock Continue?
The Triple Lock remains government policy, but there is ongoing debate about its future.
Some experts believe it should remain in place to protect pensioners from rising living costs, while others argue that reforms may be needed to balance public finances.
Any decision to change the policy would require a formal government announcement.
What Does This Mean for Future Retirees?
If you’re under 55, it’s worth thinking beyond the State Pension when planning for retirement.
Many financial advisers recommend building additional retirement savings through:
- Workplace pension schemes.
- Private pension contributions.
- Individual Savings Accounts (ISAs).
- Other long-term investments.
Relying solely on the State Pension may not provide the level of income needed in retirement.
Should You Take Action Now?
There is no need to panic, but reviewing your retirement plans is a sensible step.
You may wish to:
- Check your State Pension forecast.
- Review your National Insurance contribution record.
- Increase workplace or private pension contributions if possible.
- Stay informed about future Government announcements on pension policy.
Starting early can make it easier to adapt if pension rules change in the future.
Common Misunderstandings
Some headlines suggest people under 55 will definitely have to wait much longer for their State Pension.
That is not currently the case.
While future reviews may recommend changes, no new State Pension age has been confirmed specifically for everyone aged 55 and under. Any reforms would normally be introduced gradually and announced well before they take effect.
Final Thoughts
The latest Triple Lock update has once again highlighted the importance of long-term retirement planning for younger workers. Although current pensioners continue to benefit from annual increases, people aged 55 and under should remain aware that the State Pension age and retirement rules may change before they become eligible.
Keeping track of official Government announcements, checking your State Pension forecast and building additional retirement savings can help ensure you’re better prepared for whatever changes the future may bring.