Some people receiving the UK State Pension could be entitled to additional financial support worth more than £200 a week, depending on their income and circumstances.
The support comes through Pension Credit, a separate benefit designed to help people over State Pension age who are on a low income.
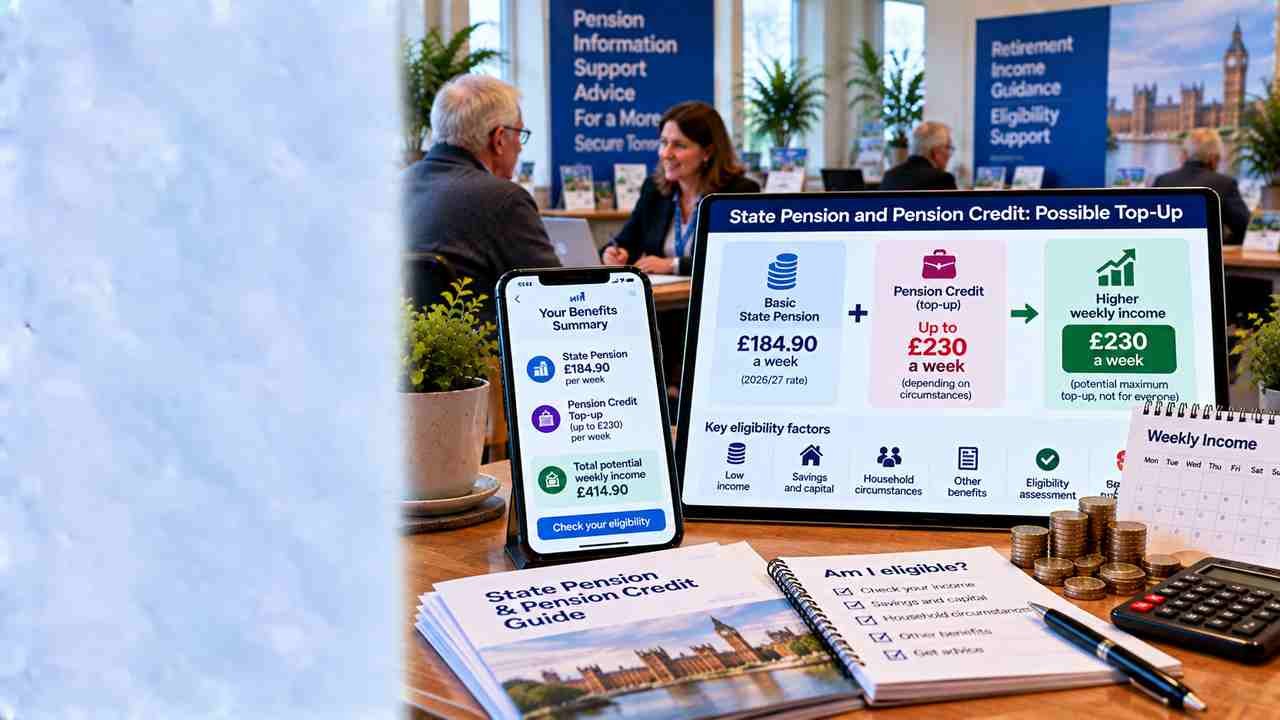
For 2026/27, the standard minimum guarantee for a single person is £238 a week, while the rate for a couple is £363.25 a week. However, this does not mean every person receiving the basic State Pension will automatically receive an extra £230 or £238 in their bank account. Pension Credit works by topping up qualifying income to the applicable minimum level.
This means some pensioners with a relatively low State Pension and other income could potentially receive additional Pension Credit each week.
What Is the £230-a-Week Extra Payment?
The headline figure can be confusing because there is no universal £230 weekly bonus payment for everyone on the basic State Pension.
Instead, Pension Credit is an income-related benefit.
For a single pensioner who qualifies for the standard Guarantee Credit, the government can top their weekly income up to £238 under the 2026/27 rates. The actual Pension Credit award is based on how much qualifying income they already have.
For example, someone with £180 a week of relevant income could potentially receive a larger Pension Credit top-up than someone whose income is already £220 a week.
The important point is that the £238 figure is the minimum guarantee level, not a flat payment on top of the State Pension.
Who Could Get Pension Credit?
Pension Credit is available to people who have reached State Pension age and meet the relevant income and residence rules.
For people living in England, Scotland or Wales, GOV.UK states that a person must have reached State Pension age to qualify. If they have a partner, their circumstances are generally assessed together.
Having a State Pension does not automatically prevent someone from claiming Pension Credit.
In fact, State Pension income is taken into account when calculating entitlement, and people with a relatively low State Pension may still qualify for additional support.
How Much Could a Single Pensioner Get?
For 2026/27, the standard Pension Credit guarantee for a single person is £238 per week.
This is important for pensioners whose weekly income is below that level.
For example, if a qualifying single pensioner has £180 a week in income that is taken into account, a simple illustration would be a potential top-up of around £58 a week to reach the standard guarantee.
The actual calculation can be more complicated because Pension Credit takes account of different types of income, circumstances and additional amounts.
Therefore, pensioners should not assume that their entitlement will simply be the difference between their State Pension and £238.
What About Couples?
Couples can also qualify for Pension Credit.
For 2026/27, the standard minimum guarantee is £363.25 a week for a couple.
When a pensioner has a partner, their income is normally considered jointly.
This means the amount someone receives cannot be worked out simply by looking at one person’s State Pension.
The household’s circumstances need to be considered.
Does the Basic State Pension Affect Eligibility?
Yes.
The State Pension is counted as income when Pension Credit is calculated. GOV.UK confirms that income can include State Pension, other pensions, employment income and certain benefits.
This does not mean that receiving the State Pension automatically rules someone out.
A person can still qualify if their overall income is low enough or if they meet conditions for additional Pension Credit amounts.
The amount of State Pension someone receives can therefore affect the size of any Pension Credit award.
Who Gets the Basic State Pension?
The old basic State Pension applies to people who reached State Pension age before the introduction of the new State Pension.
GOV.UK says the basic State Pension is generally for men born before 6 April 1951 and women born before 6 April 1953, subject to the relevant National Insurance rules. People born on or after those dates generally claim the new State Pension instead.
This distinction matters because not every current pensioner is receiving the basic State Pension.
Many people reaching State Pension age now receive the new State Pension instead.
Could Savings Stop You Getting Pension Credit?
Having savings does not automatically mean that a pensioner cannot receive Pension Credit.
GOV.UK states that savings and investments of £10,000 or less do not affect Pension Credit. Where savings exceed £10,000, the calculation takes account of the excess when assessing income.
This means pensioners should not automatically assume they are ineligible simply because they have money saved in a bank account.
The calculation depends on the person’s complete financial circumstances.
Extra Amounts May Be Available
Some people can receive more than the standard Pension Credit amount because of their circumstances.
For example, someone with a severe disability could receive an additional amount. Under the 2026/27 rates, the standard additional amount for severe disability is £86.05 a week for a single claimant.
There is also an additional amount for people who are carers. The 2026/27 rate is £48.15 a week where the relevant conditions are met.
Housing costs can also affect the calculation in some circumstances.
This is why two pensioners with similar State Pension payments could potentially receive different amounts of Pension Credit.
Pension Credit Is Separate From State Pension
One of the most important points for pensioners is that Pension Credit is not an increase to the State Pension itself.
It is a separate benefit.
The State Pension is based largely on a person’s National Insurance record, while Pension Credit is designed to provide additional help for people over State Pension age who have a low income.
Therefore, headlines describing Pension Credit as an extra payment on top of the State Pension should not be interpreted as a new State Pension rate.
Other Support Could Be Available
Getting Pension Credit can also open the door to other forms of support.
GOV.UK says people receiving Pension Credit may be able to get help such as Housing Benefit, Council Tax Reduction, Support for Mortgage Interest and help with certain NHS costs.
There can also be help with heating costs and other household expenses, depending on the individual’s circumstances and the specific scheme.
For some pensioners, these additional forms of support could be just as important as the weekly Pension Credit payment.
How Can Pensioners Check If They Qualify?
Pensioners who are unsure whether they qualify can use the official Pension Credit information and calculator on GOV.UK.
It is worth checking even if someone receives the State Pension, has some savings or owns their home.
GOV.UK specifically states that having savings or owning a home does not necessarily prevent someone from receiving Pension Credit.
The calculation considers the individual’s circumstances rather than applying a simple rule based only on whether they receive the State Pension.
Pensioners Should Not Miss Out
The key message is that the £230-a-week figure should not be understood as a guaranteed extra payment for every person receiving the basic State Pension.
Instead, eligible pensioners could receive Pension Credit to top up their income.
For 2026/27, the standard guarantee is £238 a week for a single person and £363.25 a week for a couple, with additional amounts potentially available in certain circumstances.
Someone receiving a low State Pension may therefore be entitled to additional money each week, even if they have never claimed Pension Credit before.
Checking eligibility could be particularly important for pensioners whose household income is close to the relevant threshold.
The Bottom Line for UK Pensioners
There is no automatic £230 weekly payment for everyone on the basic State Pension.
The support referred to in headlines relates to Pension Credit, which is a separate income-related benefit.
For 2026/27, qualifying single pensioners can have their income topped up to £238 a week, while qualifying couples can have their joint income topped up to £363.25 a week under the standard Guarantee Credit rates.
The amount any individual receives depends on their income, savings, relationship status and other qualifying circumstances.
Pensioners who think they may qualify should check the official Pension Credit rules rather than assuming that receiving the State Pension means they cannot get extra help.