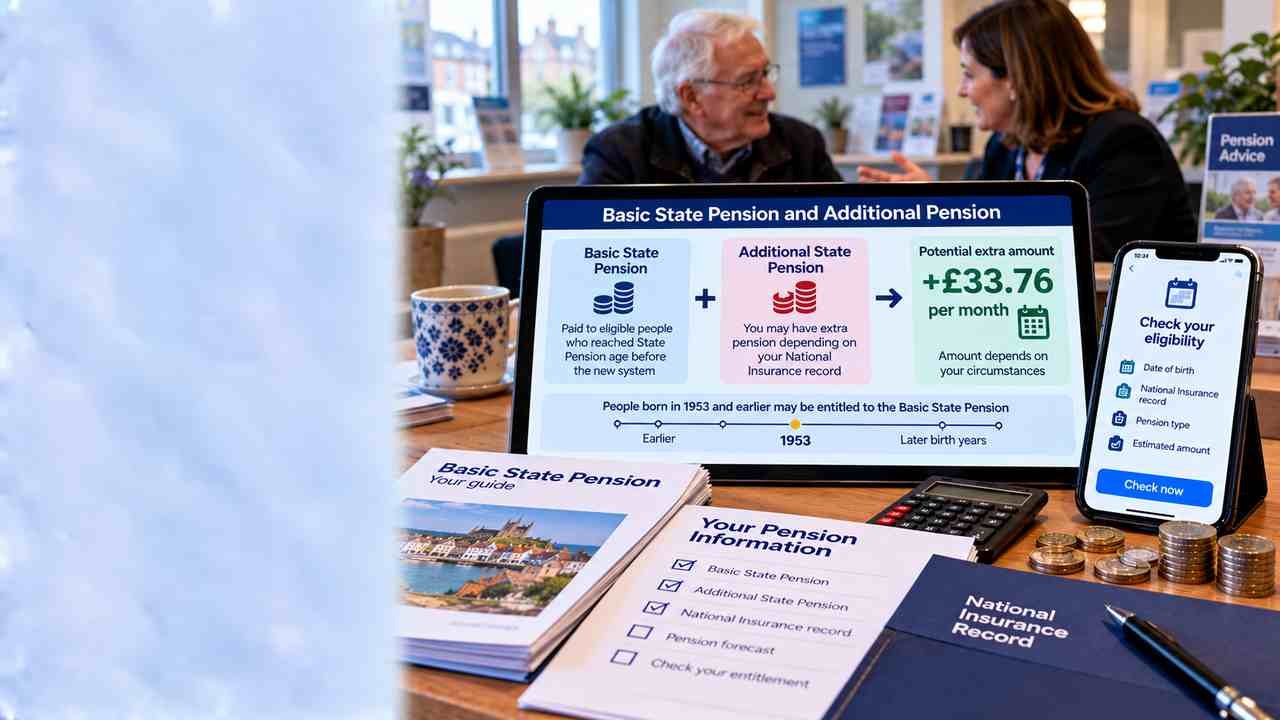
Some older UK pensioners could be entitled to extra State Pension support because of historic National Insurance rules, but the widely quoted £33.76 a month figure should not be treated as a guaranteed payment.
For people who reached State Pension age under the old system, the amount they receive depends heavily on their National Insurance record. Some older men may also benefit from automatic National Insurance credits covering certain years before retirement.
This can make a difference to the amount of basic State Pension they are entitled to.
The rules are particularly relevant to people who were born before the introduction of the new State Pension, although the exact qualifying dates differ for men and women.
Who Gets the Basic State Pension?
The old basic State Pension applies to people who reached State Pension age before the new State Pension system was introduced.
GOV.UK says a person generally receives the basic State Pension if they are a man born before 6 April 1951 or a woman born before 6 April 1953. People born on or after those dates generally fall under the new State Pension system instead.
The amount is not automatically the same for everyone.
A person’s National Insurance record determines how much basic State Pension they receive.
For the current published rate, the full basic State Pension is £184.90 a week. Someone with fewer than the required qualifying years may receive less.
Why Being Born Before 1953 Matters
The date of birth can determine which State Pension rules apply.
People who reached State Pension age before 6 April 2016 generally fall under the old system, which included the basic State Pension and potentially an Additional State Pension.
People reaching State Pension age from 6 April 2016 onwards are generally covered by the new State Pension system.
This means a person born before 1953 may have pension rights that are different from those of a younger pensioner.
However, being born before 1953 does not automatically qualify someone for an extra £33.76 every month.
The actual amount depends on their individual record.
The Automatic Credit Rule Some Men Could Benefit From
There is a particularly important rule for some older men.
GOV.UK says men born before 6 October 1953 may be entitled to automatic National Insurance credits for certain tax years when they were aged between 60 and 64.
The purpose of these credits is to help fill gaps in the National Insurance record for certain years.
A man can potentially qualify if, during the relevant years, he:
- was not working;
- was not earning enough to pay or be treated as paying National Insurance; or
- otherwise met the conditions set out by the government.
The number of credits depends on the person’s date of birth.
How Many Credits Could Be Added?
The government has a specific table for men born before 6 October 1953.
For example:
- Men born before 6 October 1950 can receive credits for five years.
- Men born before 6 October 1951 can receive four years.
- Men born before 6 October 1952 can receive three years.
- Men born before 6 July 1953 can receive two years.
- Men born before 6 October 1953 can receive one year.
These credits relate to specific tax years when the person was aged 60 to 64.
This is potentially important because National Insurance qualifying years can affect the amount of basic State Pension a person receives.
Does One Extra Year Mean £33.76 a Month?
Not necessarily.
This is where pension headlines can become confusing.
The value of an additional qualifying year depends on which pension rules apply and the person’s existing record.
The government does not state that every man receiving one of these automatic credits will receive exactly £33.76 extra every month.
Therefore, pensioners should not assume that the automatic credit is worth a fixed £33.76 monthly payment.
Instead, the credit can improve the person’s qualifying record and potentially increase their State Pension entitlement.
How Is the Basic State Pension Calculated?
The old basic State Pension is linked to National Insurance qualifying years.
For people covered by the old system, the number of years needed for the full basic State Pension depends on their circumstances and date of birth.
GOV.UK says men born between 1945 and 1951 usually need 30 qualifying years for the full basic State Pension, while men born before 1945 usually need 44 years. Women born between 1950 and 1953 usually need 30 years, while women born before 1950 usually need 39 years.
There are special rules and exceptions, so the exact calculation can differ between individuals.
What Is the Additional State Pension?
Some older pensioners may also have an Additional State Pension on top of their basic State Pension.
GOV.UK says this applies to eligible men born before 6 April 1951 and women born before 6 April 1953.
The Additional State Pension was linked to earnings and National Insurance contributions under the old system.
It can therefore provide another source of retirement income for some people.
The amount varies according to the person’s employment and National Insurance history.
Contracting Out Could Make a Difference
Some people covered by the old State Pension system were contracted out of part of the additional State Pension arrangements.
This can affect how their pension entitlement was calculated.
GOV.UK notes that people who were contracted out may have different Additional State Pension circumstances.
For this reason, two people with similar employment histories may not necessarily receive the same State Pension amount.
Could You Be Missing Pension Credits?
Older pensioners who think their National Insurance record contains gaps should check their official State Pension information.
This is particularly relevant for men born before 6 October 1953 because of the automatic credit rules.
If the relevant credits apply but are not reflected in the person’s record, the Pension Service can provide information about what should be included.
GOV.UK specifically says eligible men should add the relevant credit years when using the State Pension calculator.
What If You Have Already Retired?
Retiring does not necessarily mean there is nothing left to check.
A pensioner’s entitlement can depend on information held in their National Insurance record.
If someone believes they have missing qualifying years or has discovered that an automatic credit may apply, they can check their record and contact the Pension Service.
The key is not to assume that an advertised monthly figure applies automatically.
Can Women Born Before 1953 Qualify?
Women born before 6 April 1953 generally fall under the old basic State Pension system.
However, the specific automatic National Insurance credit rule highlighted by GOV.UK applies to men born before 6 October 1953.
This distinction is important.
A headline saying everyone born before 1953 can claim the same extra payment would therefore be inaccurate.
Women’s State Pension entitlement is determined by the rules applicable to their date of birth and National Insurance record.
What About People Born After 1953?
People born after the relevant old-system dates may fall under the new State Pension system.
For men born on or after 6 April 1951 and women born on or after 6 April 1953, the new State Pension rules generally apply.
Under the new system, people usually need at least 10 qualifying years on their National Insurance record to receive any new State Pension, subject to the relevant rules and exceptions.
The amount then depends on their National Insurance record.
What Should Pensioners Check?
Anyone who thinks they may be entitled to more should check their National Insurance history rather than relying on an online headline.
It is worth checking:
- date of birth;
- National Insurance record;
- number of qualifying years;
- basic State Pension entitlement;
- Additional State Pension entitlement;
- whether any automatic credits have been included;
- whether there are gaps in the record.
For eligible older men, the automatic credit rule could be particularly relevant.
How Can You Check Your State Pension?
The government provides State Pension information and calculators through GOV.UK.
People can check their State Pension forecast and National Insurance record to understand how their entitlement has been calculated.
For older people covered by the basic State Pension, the government also provides specific information about the old system.
If something appears incorrect, the Pension Service can be contacted for clarification.
Could the Extra Money Be Paid Automatically?
Where someone is already receiving the correct State Pension and an entitlement is identified automatically, the relevant adjustment can be made through the normal pension system.
However, pensioners should not expect a separate payment labelled “£33.76” simply because they were born before 1953.
The exact effect of additional qualifying years depends on the individual’s pension record.
This is why checking the official record is more reliable than using a fixed monthly figure.
Why Pensioners Should Check Their Records
Even a relatively small increase in weekly pension income can add up over a full year.
For someone who is entitled to additional State Pension because of a previously missing qualifying year or another adjustment, correcting the record could potentially increase their regular income.
But the increase will vary.
The government does not publish a universal £33.76 monthly entitlement for everyone in this age group.
Other Support May Also Be Available
Pensioners on a low income should also check whether they could qualify for Pension Credit.
Receiving the State Pension does not automatically rule someone out.
Pension Credit is separate from the State Pension and is designed to provide additional support for people over State Pension age who have a low income.
Someone with a relatively low State Pension could therefore potentially qualify for further financial help depending on their circumstances.
The Bottom Line
The headline figure of £33.76 a month should not be treated as a guaranteed extra State Pension payment for everyone born before 1953.
The actual rules are more specific.
People covered by the old basic State Pension system can have their entitlement affected by their National Insurance record. In particular, men born before 6 October 1953 may qualify for automatic National Insurance credits for certain years when they were aged 60 to 64.
These credits could improve a person’s qualifying record and potentially increase their State Pension entitlement.
The old basic State Pension is currently worth up to £184.90 a week under the published rate, but not everyone receives the full amount. The payment depends on National Insurance qualifying years and individual circumstances.
Some older pensioners may also have an Additional State Pension on top of their basic pension.
Anyone who thinks they could be missing pension entitlement should check their National Insurance record and State Pension information through GOV.UK.
The most important thing is to check the actual entitlement on your record, rather than assuming that a fixed £33.76 monthly amount applies simply because of your year of birth.